Author: Cindy Valle

  • YMCA Harrisburg Marathon Presented By Enders

    YMCA Harrisburg Marathon Presented By Enders

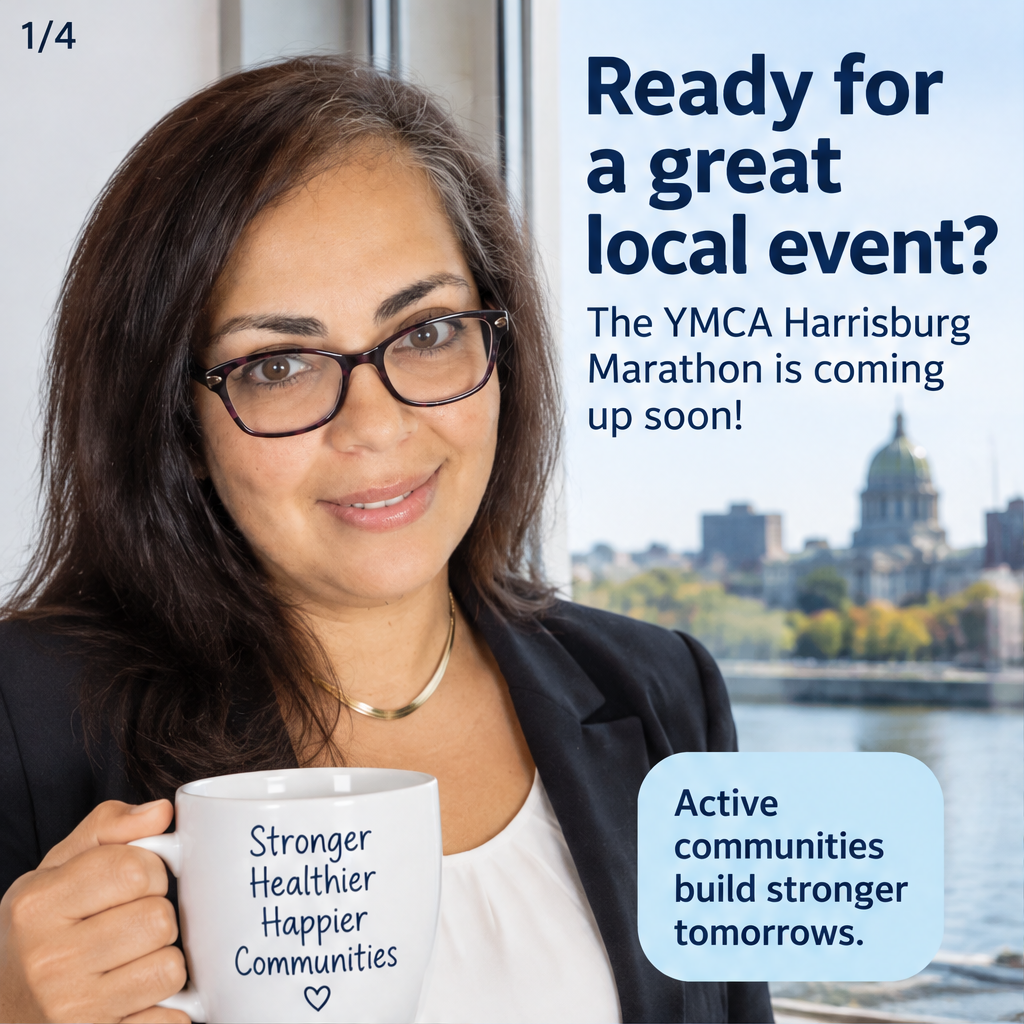
    The 54th YMCA Harrisburg Marathon, Half Marathon and 4-person Relay is scheduled for November 8, 2026, at City Island in Harrisburg, with entrances at Market and Walnut Streets. The Boston-qualifying, USATF-certified course starts and finishes on City Island, creating a clear date and location for participants and visitors to plan around.

    Marathon registration is about $105-$126. Whether you are running, supporting a participant or attending the event, planning ahead can help you organize transportation, personal belongings and other race-day activities while keeping insurance considerations in view.

    Before the event, review the coverage that may relate to your plans, including protection for belongings and other relevant personal or property needs. Coverage details vary, so consider checking your policy and discussing questions with your insurance professional.

    A local event is a useful reminder to revisit your protection before plans become busy. As November 8 approaches, take a moment to review your insurance needs and prepare for the YMCA Harrisburg Marathon, Half Marathon and 4-person Relay. Let’s review your coverage.
    Continue to full article

  • Life Insurance And Legacy Planning

    Life Insurance And Legacy Planning

    One in three U.S. workers lack a legacy plan, despite recognizing the importance of wills, powers of attorney, and healthcare directives. Many face emotional, financial, and work-related challenges after a loved one's death. Barriers to planning include uncertainty, complexity, cost, and discomfort discussing end-of-life topics. There is high demand for practical guidance and support to help workers complete essential estate planning.

    Continue to full article

  • Medicare Advantage Plans Finalize 2027 Changes

    Before October 15, review 2027 plan details, not just premiums. Drug tiers, provider networks, and specialist access can change under a familiar option.
    Start with the annual change notice sent in Late-Q3, then confirm your exact 2027 doctors, hospitals, specialists, and labs still accept the plan.
    Review every prescription for tier changes, restrictions, or approvals, then compare deductibles, copayments, coinsurance, and the annual out-of-pocket cap for covered care.
    Extra perks need scrutiny too. Dental, vision, hearing, fitness, and transportation benefits may have caps, limits, or rules; also review referrals, authorizations, and ratings.
    Use the full enrollment window. Official plan comparisons begin October 1, most changes can be made through December 7, and approved coverage starts January 1.

  • 2027 COLA Could Outpace Medicare Premiums

    In 2026, retirement benefits got a ~3% cost-of-living bump, adding about $56 to the avg. monthly check for recipients across the US.
    But standard Part B premiums ↑nearly 10%, swallowing about one-third of that increase and showing why retirees should budget from net benefits, not headline adjustments.
    Current projections suggest 2027 could be friendlier: the advocacy group expects a ~3%-4% benefit adjustment, while the program's trustees projected Part B premiums ↑~3%.
    Those figures remained estimates. An official 2027 benefit update was due in Mid-Fall, with the actual Part B premium increase expected later.
    For planning, underestimate how much of any raise will reach your bank, review budgets early, and prepare for current open enrollment running Oct. 15-Dec. 7.

  • Cash Surrender Value Explained

    Cash surrender value is the payout received when a permanent life insurance policy is terminated or matures, after building cash value over time.
    To estimate it, add guaranteed cash value and any earnings or dividends, then subtract surrender charges that can apply during a policy waiting period.
    Surrendering can free up money and end future premiums, but it also gives up the death benefit and may create fees or taxes.
    Whether surrendering makes sense depends on financial goals, beneficiary needs, and whether the cash is more useful elsewhere than inside the policy.
    If you replace surrendered coverage, you may need a new application, and insurers may consider that prior surrender alongside new policy fees too.

  • What Makes Mortgage Insurance a Supportive Career Line

    What Makes Mortgage Insurance a Supportive Career Line

    A career in mortgage insurance offers stability, professional growth, and the chance to impact homeownership by helping borrowers without traditional down payments. The sector involves bridging lenders and borrowers, supporting the economy, and adapting to evolving regulations. It provides ongoing learning, competitive compensation, benefits, work-life balance, and job security, making it a rewarding choice for those interested in finance, customer service, and risk assessment.

    Continue to full article

  • How Annuity Agents Build Long-Term Planning Skills

    How Annuity Agents Build Long-Term Planning Skills

    Annuity agents must master various annuity products and regulatory knowledge to offer tailored retirement solutions. They need strong interpersonal and analytical skills to assess clients' financial situations, risk tolerance, and goals. Building trust through ongoing communication and regular reviews is essential. Continuous education and client-focused service help agents maintain long-term relationships, ensuring clients' financial security and fostering loyalty for sustained success.

    Continue to full article

  • Happy Halloween

    Halloween falls on October 31 because the ancient Gaelic festival of Samhain, considered the earliest known root of Halloween, occurred on this day.
    In the eighth century, Pope Gregory III designated November 1 as a time to praise all saints.
    Soon, All Saints' Day incorporated some traditions of Samhain and the evening before was known as All Hallows Eve, and later Halloween.
    Over time, Halloween evolved into a day of activities like trick-or-treating, carving jack-o-lanterns, festive gatherings, donning costumes and eating treats.
    Today’s the day to eat candies and sweets to your heart’s content! Happy Halloween!

  • Term Life Insurance Is Most Affordable

    In US pricing, term life remained the lowest-cost option because coverage is temporary and lacks cash value, with 10-yr starter premiums near ~$11/mo to ~$13/mo.
    One insurer posted the lowest sample rates across 10-yr, 20-yr, and 30-yr term policies for applicants seeking $500K, though 30-yr options usually ended at 60.
    Costs depended on age, gender, health, tobacco use, policy type, term length, and death benefit, so identical coverage can price differently across applicants.
    Permanent coverage cost more because it builds cash value; universal life was cheapest, while whole, indexed, and final expense each had category leaders.
    Best-rate steps included choosing term when appropriate, sizing coverage carefully, comparing quotes, limiting optional riders, and answering medical questions honestly with professional guidance.

  • Why Medicare Bills Still Show Up

    Medigap helps with many Medicare out-of-pocket costs, but it does not make every approved service or every healthcare expense automatically cost $0.
    A common early-year bill is the 2026 Part B deductible: $283. Plan G beneficiaries generally pay it before Medicare and Medigap share covered costs.
    Your Medigap letter matters: Plans K and L can cover only part of cost sharing, while Plan N may add office and ER copays.
    Many surprise bills come from services Medicare generally excludes, including routine dental, vision, hearing aids, long-term custodial care, or prescriptions handled separately through Part D.
    Before paying, compare the provider bill, Medicare Summary Notice, and Medigap benefits statement to confirm deductibles, claim approval, supplement processing, or possible errors.